Updated September 2026
You found the house. Or you found four of them, and you can't tell yet which one is real.
That's roughly where most first-time buyers in Alexandria are standing when they call us. Not confused about what they like. Confused about what they're actually able to do about it, and whether an offer from a first-time buyer even gets a serious read in this city.
It does.
The first-time buyers who get to the settlement table here usually did three quiet things before they wrote anything. They lined up the right loan product. They checked whether they qualified for money they didn't know existed. And they wrote terms that made the seller's decision easy. Price is one lever. It's rarely the one that decided it.
The short version
- The median sale price in Alexandria City, Virginia was $707,000 in July 2026, according to Bright MLS data in Long & Foster's August 2026 market report for Alexandria City, so the down payment question matters more than the rate anyone quotes you at a party.
- Virginia Housing runs first-time buyer loans and down payment assistance statewide. The City of Alexandria's Office of Housing runs its own homeownership assistance for income-eligible buyers. These are separate programs with separate applications.
- If you're VA-eligible, the VA loan is the strongest tool available to a first-time buyer in this region, and most of the reasons sellers used to flinch at it are out of date.
- Competing well here is mostly about terms and certainty. It is not only about the number.
What a first purchase in Alexandria looks like right now
Start with the actual field you're playing on. In July 2026, the median sale price in Alexandria City, Virginia was $707,000, and 171 homes sold, per the August 2026 Long & Foster Community Market Report for Alexandria City, with data from Bright MLS. As of August 14, 2026, there were 399 homes for sale in the city.
Alexandria City, Virginia. July 2026 closings and the August 14, 2026 inventory snapshot, from the August 2026 Long & Foster Community Market Report for Alexandria City. Data: Bright MLS.
Metric | Value | Period | Source |
|---|---|---|---|
Median sale price | $707,000 | July 2026 | Bright MLS |
Homes sold | 171 | July 2026 | Bright MLS |
Homes for sale | 399 | As of August 14, 2026 | Bright MLS |
One boundary note before you do any math on those figures. They describe the independent City of Alexandria. A great many mailing addresses read Alexandria and sit in Fairfax County, outside the city line. City figures, city taxes, and city homeownership programs follow the jurisdiction, not the envelope. If you're not sure which side of the line a listing is on, check before you build a plan around it.
The second thing worth knowing is how Alexandria sits next to its neighbors. The August 2026 Long & Foster market reports for those areas put the July 2026 median sale price at $731,000 in Fairfax, Virginia and $827,450 in Arlington, Virginia, both above Alexandria's $707,000 in the same month. Bright MLS labels that middle market simply Fairfax, Virginia, so read it as their label rather than a specific city or county line. For a first-time buyer choosing between close-in options, Alexandria is often the one where the entry price and the commute both work.
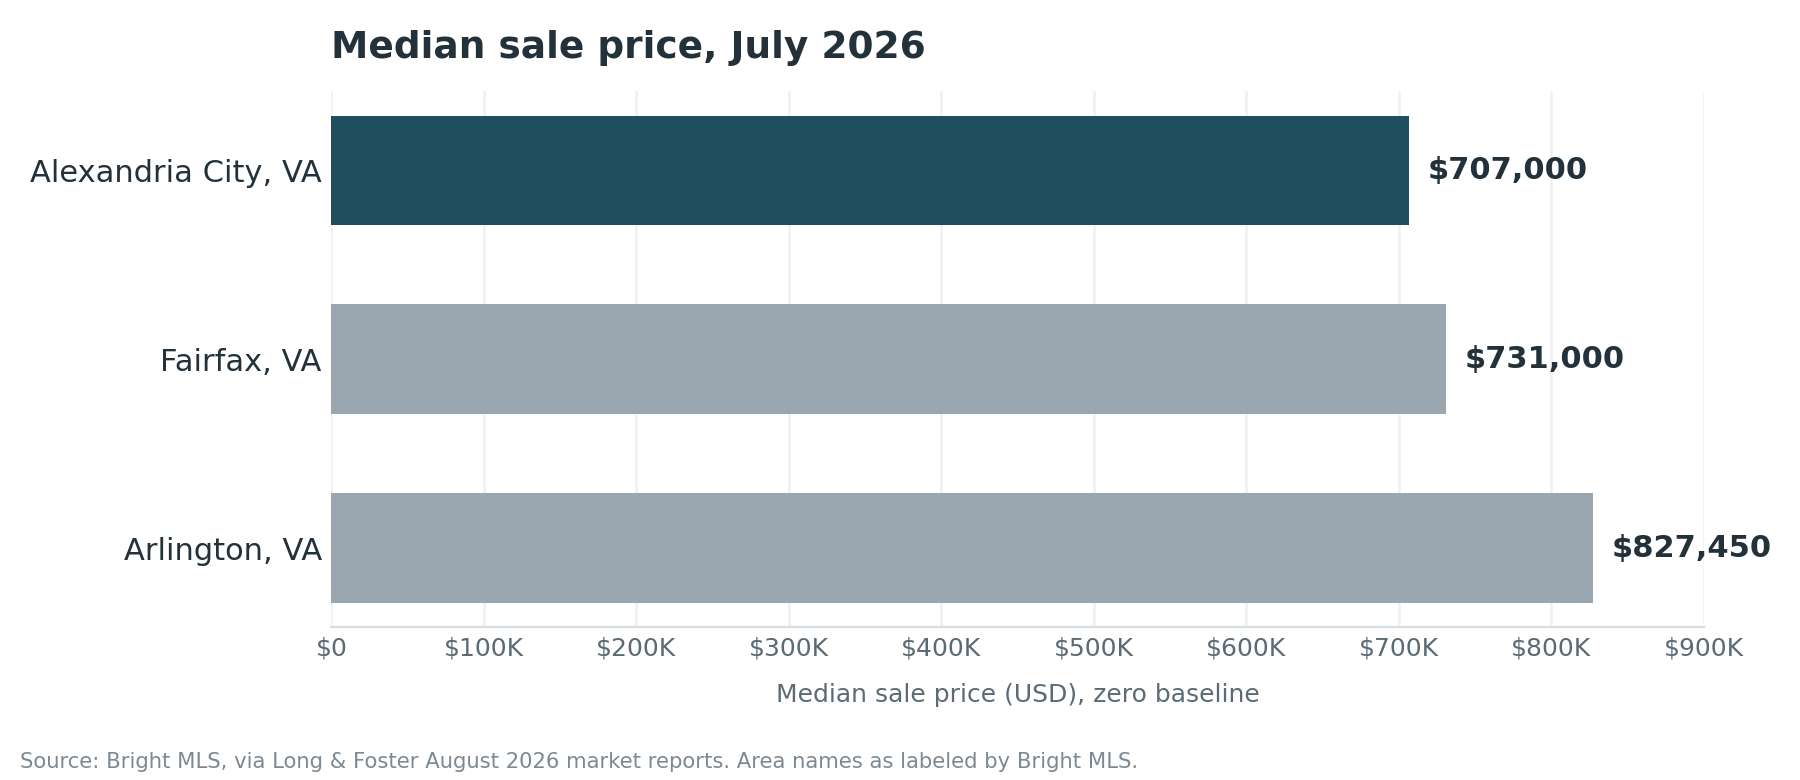
Chart 1. Median sale price, July 2026, three Northern Virginia markets as labeled by Bright MLS. Zero baseline. Source: Bright MLS.
Money you may qualify for and never hear about
This is the part most first-time buyers skip, usually because they assume assistance is only for someone else. Check anyway. The eligibility ceilings are higher than people expect, and finding out costs you one conversation.
Virginia Housing
Virginia Housing is the state's housing finance authority, and it's the first stop. It offers loans built for first-time buyers, down payment assistance, and a second-mortgage option that covers part of the cash you'd otherwise need at settlement. Most of its programs require a homebuyer education course, which is free, online, and genuinely useful the first time through.
Two things to know about how it works. Virginia Housing doesn't lend to you directly. You go through a participating lender, and not every lender in the region is one, so ask that question early. And the programs carry income and sales price limits that vary by area and change periodically. Ask a participating lender to run your numbers rather than reading a summary and deciding you're out.
The City of Alexandria's Office of Housing
The city runs its own homeownership assistance for income-eligible first-time buyers, separate from anything the state does, and it sometimes has set-aside units in new developments that never look like a deal from the outside. Start at the City of Alexandria Office of Housing.
Program names, income ceilings, and funding availability shift from year to year and funding can run out mid-year, so confirm current terms directly with the Office of Housing rather than relying on any summary, including this one.
FHA and low down payment conventional loans
If the assistance programs don't fit, the low down payment options still do. FHA loans allow a smaller down payment and are more forgiving on credit history, with the tradeoff that mortgage insurance is part of the payment and, at low down payments, generally stays for the life of the loan. Conventional programs like Fannie Mae's HomeReady and Freddie Mac's Home Possible also allow low down payments, and their private mortgage insurance can come off once you've built enough equity.
Which one wins depends on your credit profile, your cash, and how long you plan to hold. That's a lender conversation, not a blog conversation, and we're not licensed to quote you a rate. What we will say is that in a market at this price point, the difference between the right product and the merely available one is real money.
The VA loan, used the way it was designed
Alexandria is a military and federal town. Fort Belvoir, the Mark Center, the Pentagon, and the Navy Yard across the river all put VA-eligible buyers in this market every month, and a surprising number of them shop with a conventional pre-approval because someone told them a VA offer wouldn't get accepted.
What it actually does
The VA home loan is backed by the U.S. Department of Veterans Affairs and is available to eligible veterans, active-duty service members, many Guard and Reserve members, and some surviving spouses. For an eligible borrower with full entitlement, it requires no down payment. It carries no monthly mortgage insurance, which is the piece people underestimate, because that's a permanent difference in the monthly payment rather than a one-time savings.
There's a one-time VA funding fee, which can be financed into the loan, and it's waived for borrowers receiving VA compensation for a service-connected disability along with certain other categories. You'll need a Certificate of Eligibility, which your lender can usually pull in minutes. VA loans are also assumable by a qualified buyer, subject to approval, which is worth remembering years from now when you're the one selling.
The seller objections that are out of date
Sellers and their agents sometimes carry old assumptions about VA financing. Three of them come up here constantly, and all three are answerable in writing.
The appraisal. VA appraisals apply minimum property requirements, and the VA amendatory clause means a VA buyer can't be forced to pay more than the appraised value. That's a protection, not a defect, and a well-maintained Old Town rowhouse or a newer condo clears it routinely. Have your lender put the timeline in writing in the offer.
Closing costs. A VA buyer can ask a seller to contribute toward closing costs, but nothing requires you to ask. If your cash position allows you to cover your own, say so on the offer, because it removes the objection entirely.
Speed. VA loans close on ordinary timelines with a lender who does them regularly. The fix is choosing that lender, not abandoning the loan.
Condos: check the approval list first
This one is Alexandria-specific and it costs people real time. A condominium has to be on the VA's approved list for a VA loan to work there, and plenty of buildings in and around Old Town, Del Ray, and the West End are not. Getting an unapproved association added is possible, but it depends entirely on a board and a management company cooperating on a timeline that has nothing to do with yours.
So check the list before you tour, not after you write. If you're VA-eligible and shopping condos, that single step reshapes your search map more than anything else in this post.
How to compete without overpaying
Pre-approval that holds up to a listing agent's phone call
There's a real difference between a pre-qualification generated from what you typed into a website and a pre-approval where an underwriter has looked at your pay stubs, your tax returns, your credit, and your assets. In a competitive round, the listing agent calls your lender. What that lender says in ninety seconds is part of your offer whether you like it or not.
Use a lender who knows Virginia contracts, answers the phone on a Sunday afternoon, and will proactively call the listing agent to vouch for your file. Ask your agent who's actually performed for them recently. That recommendation is worth more than a rate sheet.
The terms sellers actually weigh
When a seller reviews offers, they're pricing risk. Every term that reduces their risk buys you room on the ones you care about. Our fuller treatment of how to structure a competitive offer goes term by term.
- Earnest money. A deposit that reads as serious, delivered on time, says more about you than a cover letter does. We walk through how earnest money actually works here separately.
- Their timeline, not yours. Many Alexandria sellers are buying next. Offering a post-settlement occupancy period, so they can stay after closing while they move, is often the term that wins a house without adding a dollar.
- Appraisal language you understand. Waiving the appraisal contingency and agreeing to cover a stated gap in cash are not the same thing. The second one is bounded. Know which you're signing, and never write either without a number you can actually produce.
- Inspection, handled thoughtfully. You don't have to choose between waiving inspection and losing the house. Walking the property with an inspector before you write, or using an information-only inspection, keeps your eyes open while still giving the seller certainty.
- A clean, complete package. Signed, dated, initialed, with the lender letter and proof of funds attached. Sloppy offers get read as sloppy buyers.
Where you have more room than you think
Not every listing draws a crowd. Set expectations honestly first. Alexandria City carried 2.3 months of inventory in July 2026, which is a seller's market by the report's own legend, homes sold in a median of 12 days, and 33% of July sales closed above the original asking price. We wrote up that picture in more detail in our Alexandria market pulse, and nothing in this post contradicts it.
What the aggregate hides is that two thirds of July sales did not go over ask, and there were still 399 homes on the market as of August 14, 2026. Listings that have been sitting, condos with a healthy reserve study and an unglamorous lobby, and homes that need cosmetic work are the pockets where a first-time buyer can write a normal offer with normal contingencies and have it accepted.
And set your walk-away number before you tour anything, in writing, with your name on it. The house you lose by holding that line is not the last house. There will be another.
Alexandria specifics that catch first-time buyers off guard
These are prep and disclosure items, not verdicts on any neighborhood. They're simply the things that come up here and don't come up everywhere. Budget for the cash side too: closing costs in Alexandria breaks down what buyers actually pay at settlement.
- Condo and association documents. Virginia gives you a review period once you receive the resale certificate or property owners' association packet. Read the reserve study, the minutes, and any special assessment discussion, not just the monthly fee. Order the documents the day you go under contract.
- Special flood hazard areas. Parts of the Old Town waterfront and areas near Four Mile Run sit in mapped flood zones. Check the FEMA flood map for the specific parcel and get an insurance quote before your contingencies expire, not after.
- Historic district review. Properties in the Old and Historic Alexandria District and the Parker-Gray District have exterior changes reviewed by the Board of Architectural Review. If your plan involves replacement windows, a fence, or a rear addition, build that review into your timeline and budget. We wrote about how that board shapes Old Town sales if you want the longer version.
- Marine clay soils. Portions of this area sit on marine clay, which expands and contracts with moisture and shows up in foundations, basements, and retaining walls. Ask your inspector about it directly.
- Aircraft noise. Some corridors sit under the National Airport approach. Visit at different hours and on different days before you commit.
- Parking. In much of Old Town, residential permit parking is the arrangement. A home without off-street parking isn't a problem, but it is a decision.
This is general information and is not legal or tax advice. Talk to your attorney or CPA about how any of it applies to you.
The order we'd put it in
- Talk to a lender who regularly writes VA and Virginia Housing loans in Virginia.
- Check program eligibility with Virginia Housing and the City of Alexandria's Office of Housing before you settle on a price point.
- If you're VA-eligible, pull your Certificate of Eligibility and get the VA approved condo list in front of you.
- Get a fully underwritten pre-approval, not a website pre-qualification.
- Write down your walk-away number and give a copy to your agent.
- Then start touring.
Buyers who work in that order tend to write from a settled position instead of a hopeful one. Working in reverse is how good buyers spend a spring losing houses.
When you want a second read on it
Buying your first place is one of the largest financial decisions most people ever make, and it deserves more than a search alert and hope. If you want someone to look at your pre-approval, your program eligibility, or a specific block before you write, we're glad to do that. No pressure attached to it.
Elizabeth Lucchesi and The LizLuke Team at LONG & FOSTER REAL ESTATE INC have been working these blocks for a long time, and most of our business comes from referrals and repeat clients. You can reach us through lizluke.com or by phone. It all starts with a conversation.
Elizabeth Lucchesi, The LizLuke Team. LONG & FOSTER REAL ESTATE INC. 110 N Royal St, Ste 300, Alexandria, VA 22314. 703.868.5676. Virginia License #0225069250.
Equal Housing Opportunity.
All information is deemed reliable but not guaranteed.
Sources
- Long & Foster Real Estate, "Community Market Report: Alexandria City, Virginia," August 2026. Data provided by Bright MLS and Williamsburg Area AOR MLS.
- Long & Foster Real Estate, "Community Market Report: Arlington, Virginia," August 2026. Data provided by Bright MLS and Williamsburg Area AOR MLS.
- Long & Foster Real Estate, "Community Market Report: Fairfax, Virginia," August 2026. Data provided by Bright MLS and Williamsburg Area AOR MLS.